While lithium-ion anode graphitization tolling quotes recently rose by roughly 300 RMB/ton on higher auxiliary costs, nearly 10 billion RMB in newly announced captive integrated projects scheduled to land in 10 to 12 months will structurally squeeze independent tollers.
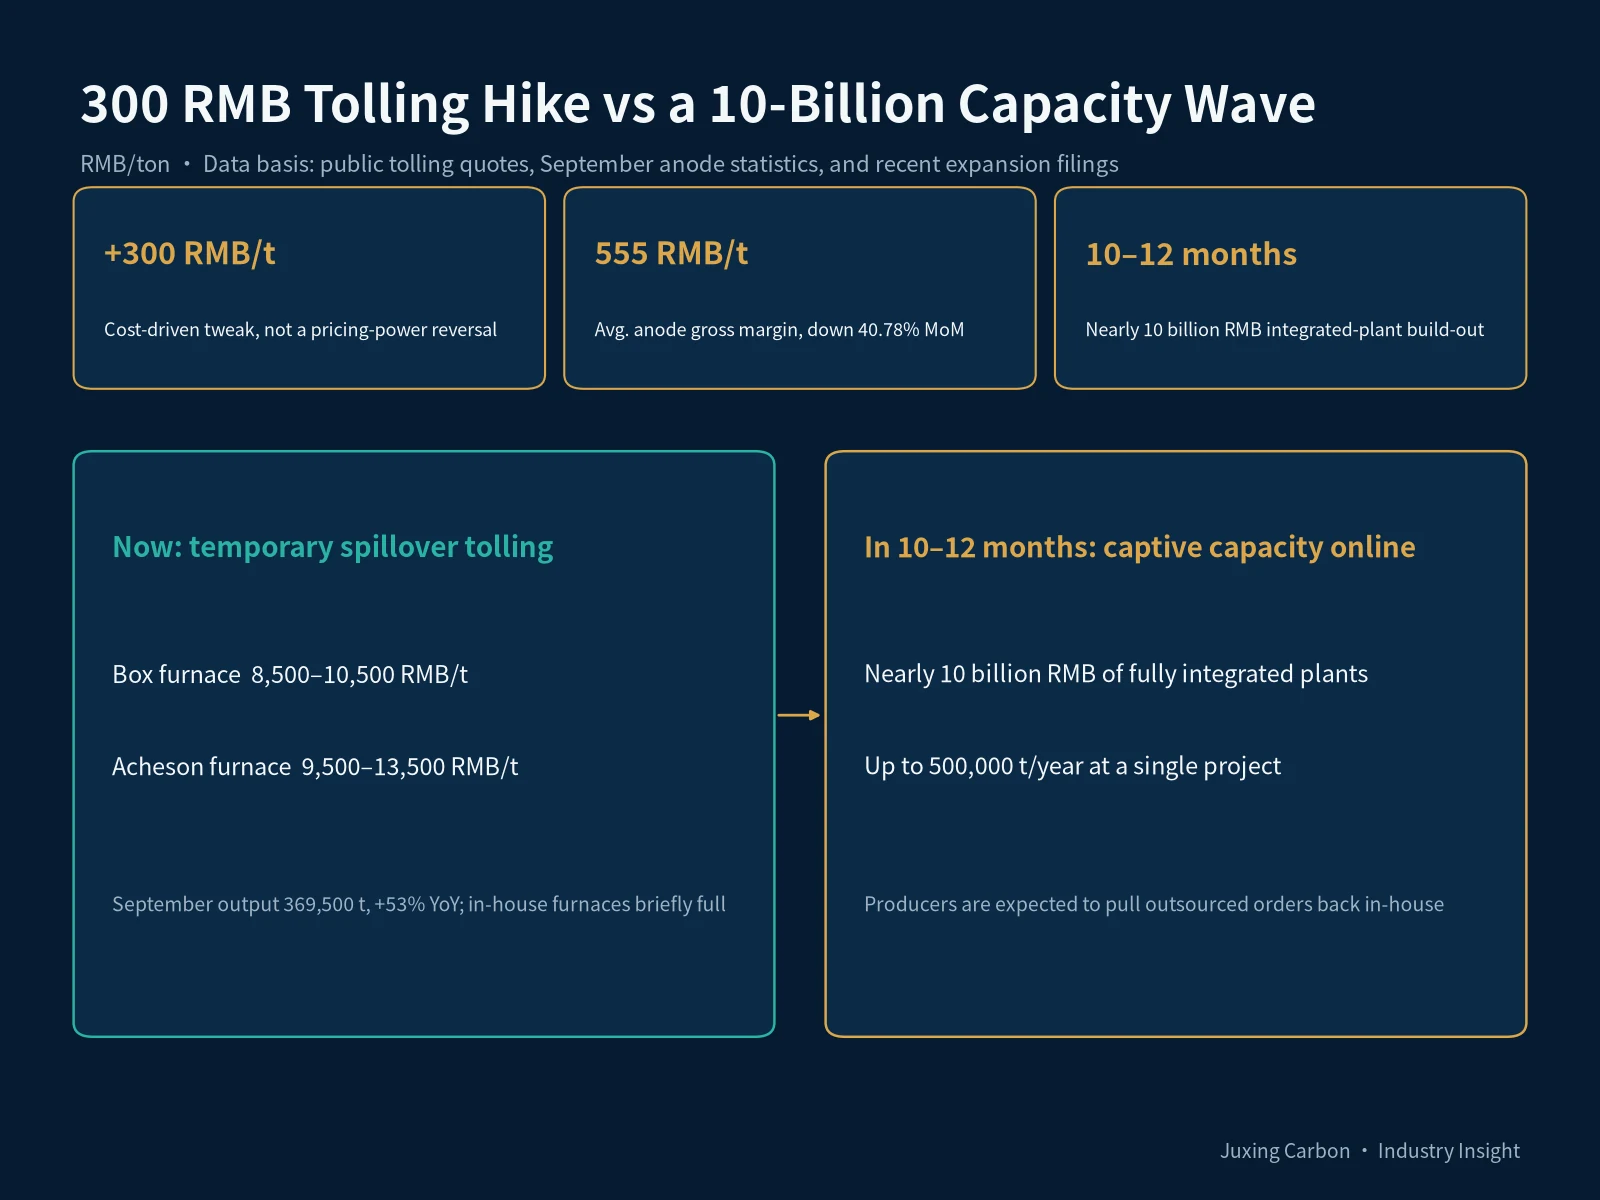
In China’s lithium-ion anode processing market, two contrasting sets of data have emerged simultaneously. On the spot quote board, outsourced anode graphitization tolling rates recently edged up by approximately 300 RMB/ton, bringing mainstream box-furnace tolling to 8,500–10,500 RMB/ton and Acheson furnace tolling to 9,500–13,500 RMB/ton. At the same time, capacity filings in northern production hubs disclosed nearly 10 billion RMB in new anode expansion investments within just two days—featuring single projects of 4.5 billion and 5.1 billion RMB, individual planned capacities of up to 500,000 tons/year, and construction timelines of 10 to 12 months.
Cost-Driven, Not a Reversal
Data basis: public tolling quotes as of November 2026, public anode industry statistics for September, and recently disclosed expansion filings.
Viewed together, these figures indicate that the 300 RMB/ton uptick on a 10,000 RMB/ton base is a cost-driven adjustment rather than a structural recovery for independent tollers. Recent increases in petroleum coke and modified pitch prices have lifted the cost of furnace insulation media, resistor coke, and carbon consumables, while autumn and winter power tariffs have added further operating pressure. The 300 RMB/ton adjustment barely offsets these incremental energy and auxiliary material expenses.
| Furnace type | Recent mainstream quotes | Vs. prior levels |
|---|---|---|
| Box furnace | 8,500–10,500 RMB/ton | Up about 300 RMB/ton |
| Acheson furnace | 9,500–13,500 RMB/ton | Quotes have lifted |
Note: The 300 RMB/ton figure is the industry-wide adjustment on a roughly 10,000 RMB/ton tolling base.
Downstream Margin Squeeze
More importantly, downstream anode makers lack the margin buffer to sustain higher external tolling fees. In September, domestic anode prices averaged 33,500 RMB/ton (with volume grades at 17,500–24,000 RMB/ton), while average production costs reached 25,745 RMB/ton—compressing the industry’s average gross profit by 40.78% month-on-month to 555.01 RMB/ton. The temporary spillover of outsourced tolling orders was triggered solely by September’s rapid output surge to 369,500 tons (up 53% year-on-year), which briefly maxed out major producers' in-house furnaces.
| Anode industry indicator | Public figure | Change |
|---|---|---|
| September average priceVolume grades at 17,500–24,000 RMB/ton | About 33,500 RMB/ton | — |
| Average production cost | About 25,745 RMB/ton | Feedstock and processing costs up |
| Average gross margin | 555.01 RMB/ton | −40.78% month on month |
| September monthly output | 369,500 tons | +53% year on year |
Note: Price, cost and margin figures follow publicly reported industry statistics; the margin is the published statistical value.
Captive Capacity Pulls Orders In-House
Looking ahead 10 to 12 months, every project in the newly announced 10-billion-RMB wave is designed as a fully integrated facility spanning raw material preparation, granulation, baking, and graphitization. Once these captive mega-furnaces are commissioned next year, major anode manufacturers will inevitably pull outsourced orders back in-house to maximize their own utilization rates. Independent graphitization plants that invest heavily to restart idled furnaces over a temporary 300 RMB/ton hike face severe utilization and pricing headwinds once captive integrated capacity comes online.
| Expansion filing | Public figure | Implication |
|---|---|---|
| New investment disclosed in two days | Nearly 10 billion RMB | Fully integrated projects |
| Single-project investment | 4.5 to 5.1 billion RMB | — |
| Planned capacity at one project | Up to 500,000 tons/year | Captive graphitization loop |
| Construction timeline | 10 to 12 months | Due online next year |
Note: Filings are from northern production hubs and cover raw-material preparation, granulation, baking and graphitization.